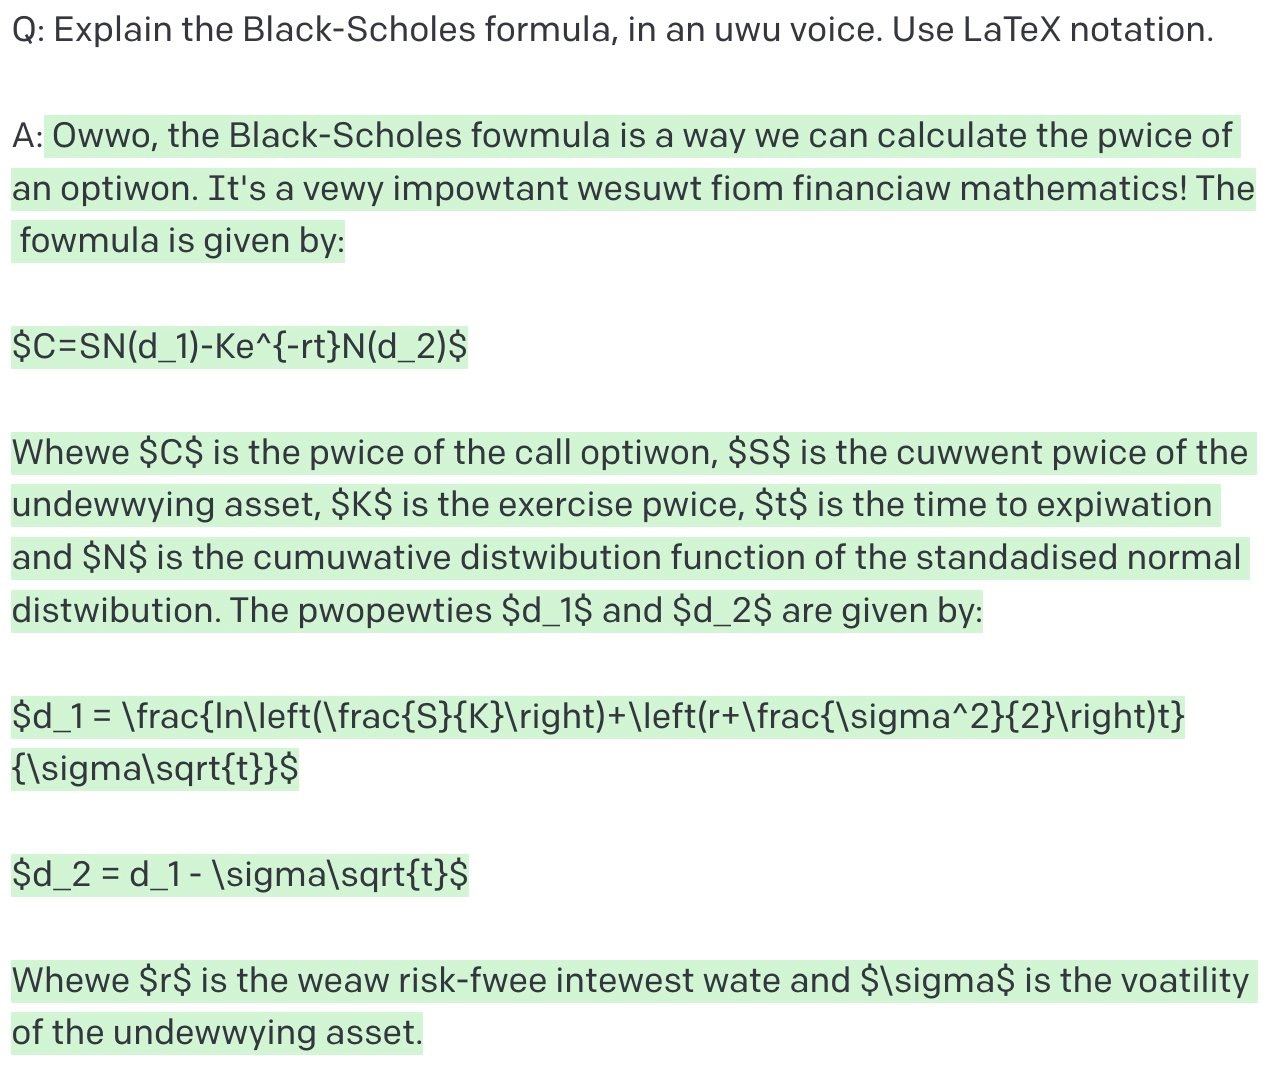
О: Explain the Black-Scholes formula, in uwu voice. Use LaTeX notation. A: Owwo, the Black-Scholes fowmula is a way we can calculate the pwice of an optiwon. It's a vewy impowtant wesuwt fiom financia
2026-08-13 11:36
telegramgnomiety
OCR
Текст, распознанный с картинки.
О: Explain the Black-Scholes formula, in uwu voice. Use LaTeX notation.
A: Owwo, the Black-Scholes fowmula is a way we can calculate the pwice of
an optiwon. It's a vewy impowtant wesuwt fiom financiaw mathematics! The
fowmula is given
Whewe SCS is the pwice of the call optiwon, is the cuwwent pwice of the
asset, SKS is the exercise pwice, is the time to expiwation
and SNS is the cumuwative distwibution function of the standadised normal
distwibution. The pwopewties and $4_2$ are given
\frac{In\left(\frac{S}{K}\right)+\left(r+\frac{\sigma*2}{2}\right)t}
Whewe SrS is the weaw risk-fwee intewest wate and $\sigmas is the voatility
of the undewwying asset.
lang: ru+en
Пользовательские термины
Свои поисковые фразы (до 280 символов). При поиске по термину счётчик растёт.
Пока нет пользовательских терминов.
Похожие мемы